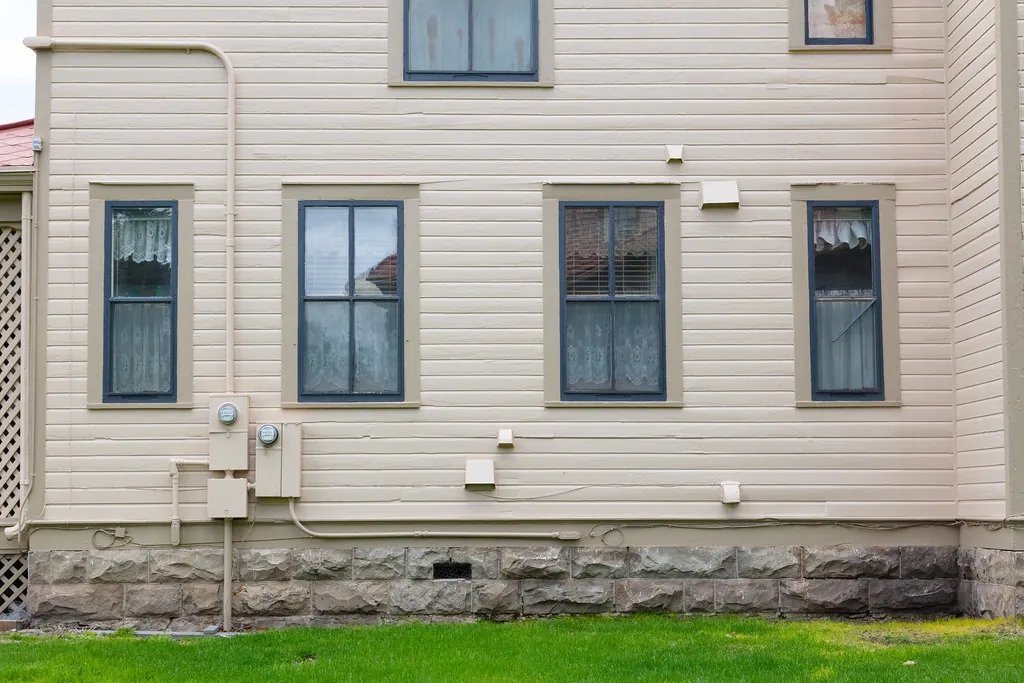
Storms rarely damage every side of a house equally. Hail may hit only the west elevation; a tornado may peel siding off one corner. The carrier offers to replace what’s damaged. The problem: the replacement doesn’t match.
Why matching disputes happen
Siding colors fade and profiles get discontinued. Shingle lines change every few years. Brick blends vary by batch. A patch that technically restores the damaged area can leave a home visibly mismatched.
What policies and rules say
Policies usually promise repair or replacement with materials of like kind and quality. How that applies to undamaged areas varies by policy language and jurisdiction, and carriers take different positions. The facts — whether a reasonable match is available — usually drive the outcome.
How to document a matching problem
- Identify the product, manufacturer and color where possible.
- Get written confirmation from suppliers that the product is discontinued.
- Photograph test pieces held against the existing material.
- Note continuous runs: siding that wraps corners, flooring that flows between rooms.
When appraisal helps
If coverage is accepted and the dispute is how much of the material must be replaced for a reasonable repair, appraisal panels often address it as part of the amount of loss. A strong record makes the difference.